
Compound Savings Calculator: The Ultimate Guide to Growing Your Money
Saving money is the foundation of financial security, but simply stashing cash under a mattress doesn’t grow your wealth. To truly build your savings, you need the power of compound interest and regular contributions. Our advanced Compound Savings Calculator goes beyond simple projections. It lets you model annual contribution increases, apply capital gains taxes, and adjust for inflation, giving you a realistic picture of your future purchasing power. Whether you’re saving for an emergency fund, a down payment, or retirement, this free tool shows you exactly how your savings will grow over time—and what they’ll be worth in today’s dollars.
Compound Savings Calculator
Why Compound Interest is the Eighth Wonder
Albert Einstein reportedly called compound interest the eighth wonder of the world. It’s the process where your interest earns its own interest, creating exponential growth. For example, if you invest $1,000 at 5% annually, after 10 years you’ll have $1,628, but after 30 years you’ll have $4,321—a massive difference. Our calculator harnesses this power by applying the exact compounding frequency you choose (daily, monthly, quarterly, or annually). The more frequent the compounding, the faster your money grows. As Investopedia explains, this is the single most important concept in investing.
How Our Advanced Calculator Works
We’ve upgraded this tool to handle the complexities of real-world saving:
- Initial Deposit: The lump sum you start with.
- Regular Contribution: How much you add periodically (monthly, quarterly, or annually).
- Contribution Frequency: How often you make deposits.
- Annual Interest Rate: The return your savings account or investment earns.
- Compounding Frequency: How often interest is calculated and added to your balance.
- Years: Your time horizon.
- Annual Contribution Increase (NEW): In reality, your income grows, so you might save more each year. This field models that.
- Tax Rate (NEW): Interest earned is often taxable. We subtract the tax from your gains to show your net balance.
- Inflation Rate (NEW): The rising cost of living erodes purchasing power. We adjust your future value to show what it’s actually worth in today’s dollars.
Real-World Example: Sarah’s Emergency Fund
Let’s test the calculator with a realistic scenario.
- Initial Deposit: $1,000
- Regular Contribution: $500/month
- Contribution Frequency: Monthly
- Annual Interest Rate: 4.5%
- Compounding Frequency: Monthly
- Years: 10
- Annual Contribution Increase: 3%
- Tax Rate: 15%
- Inflation Rate: 2.5%
Results:
- Future Balance (before tax): The calculator projects $76,400.
- Total Deposited: You’ll have contributed **$64,000** ($1,000 + $500 × 12 × 10 with increases).
- Interest Earned: $12,400.
- Tax: 15% of interest = $1,860.
- Net Future Value: $74,540.
- Real Value (Today’s $):** After inflation, the net value is only **$58,000.
This shows that while your nominal balance looks great, the real purchasing power is lower. Our calculator reveals this crucial insight.
The Power of Increasing Contributions
Saving $500 a month is great, but if you increase it by 3% each year, your contributions grow significantly. By year 10, you’ll be contributing about $650/month. Over the decade, this adds thousands of dollars to your balance. Our calculator lets you see the difference. Many financial experts recommend increasing your savings rate with every raise. The SEC emphasizes that systematic investing is key to building wealth.
Why Taxes Matter
Interest income is generally taxable. If you’re in a 15% tax bracket, you’ll owe 15% of your interest earnings each year. Our calculator applies this tax to your gains, showing you your net value. This is especially important for high-yield savings accounts (HYSA) or certificates of deposit (CDs). For a deeper dive, check our Tax Refund Calculator to understand your overall tax situation.
The Impact of Inflation
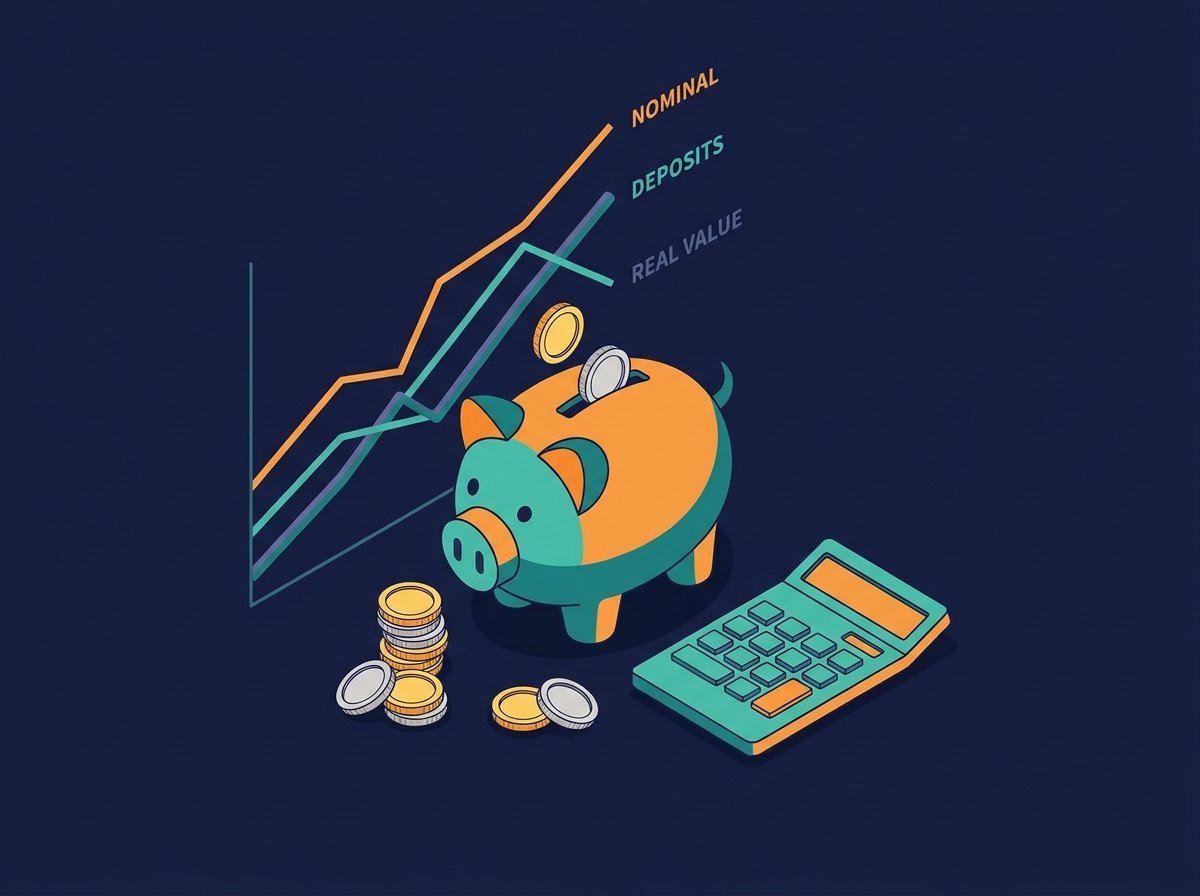
Inflation is the silent killer of savings. If inflation is 2.5%, your $74,000 in 10 years will only buy about $58,000 worth of today’s goods. This is why you need to invest in assets that outpace inflation, like stocks or real estate. Our calculator’s “Real Value” line on the chart shows you this adjustment clearly. The Bureau of Labor Statistics publishes current inflation data, which is a great resource for planning.
Using the Calculator to Set Goals
The “Target Amount” field is a game-changer. If you have a goal (e.g., saving $50,000 for a house), the calculator tells you:
- If you’re on track: It shows how many years it will take.
- If you’re behind: It calculates the extra monthly contribution needed to hit your goal within your timeframe.
For example, if your target is $50,000 and you’re starting with $1,000 and $500/month, the calculator might tell you to increase your monthly contribution to $700 to reach it in 10 years. This removes guesswork and gives you a clear action plan.
Practical Tips for Maximizing Savings
Your Next Steps: Related Tools
Understanding savings is just the beginning. Explore our suite of savings calculators:
- Savings Goal Calculator
- Emergency Fund Calculator
- High-Yield Savings Calculator
- Inflation-Adjusted Savings Calculator

5 Comments