CD Ladder Calculator: The Ultimate Guide to Locking in High Yields with Liquidity
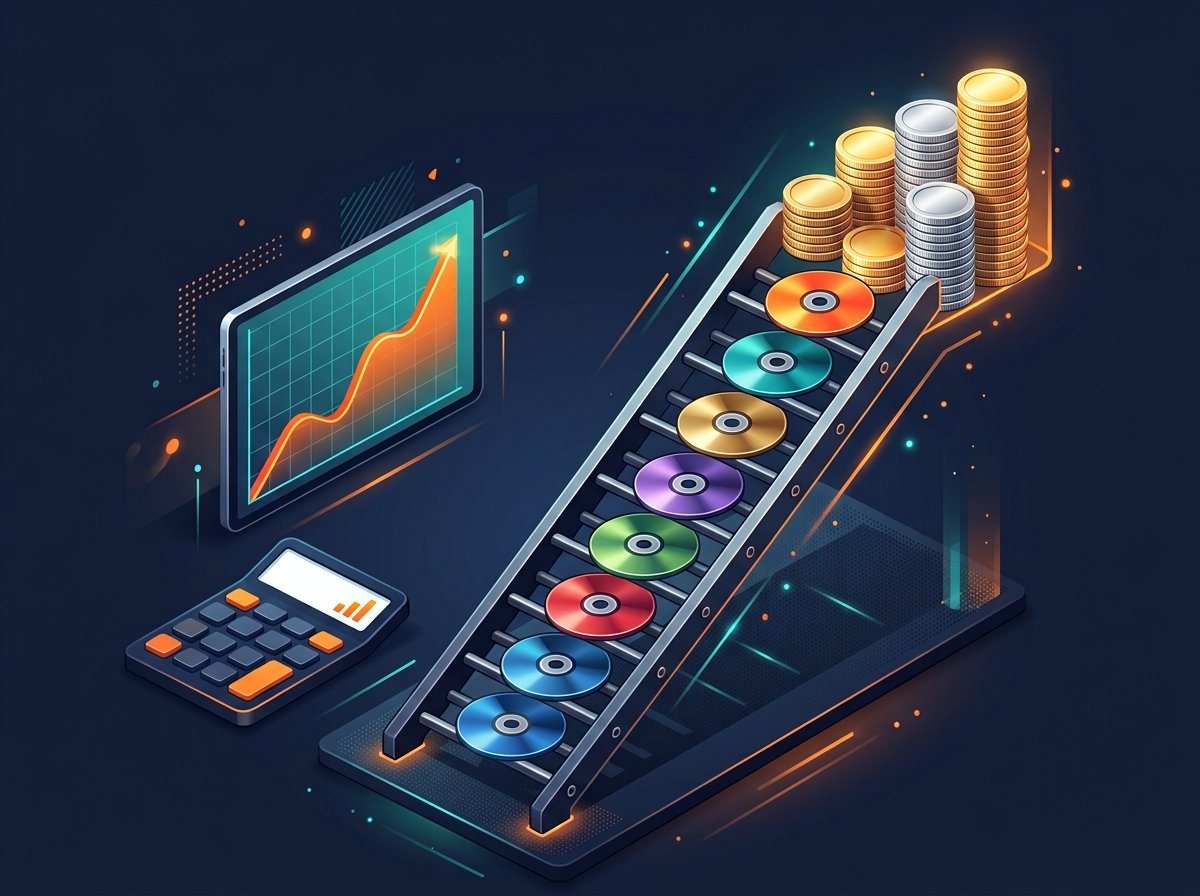
In a world of fluctuating interest rates, finding a savings strategy that offers both a high return and access to your money can feel impossible. This is where a CD ladder comes in. A CD ladder is a strategy where you divide your money into several Certificates of Deposit (CDs) with staggered maturity dates. This allows you to take advantage of higher long-term rates while keeping a portion of your funds liquid as shorter-term CDs mature. Our advanced CD Ladder Calculator has been completely redesigned. It lets you customize each rung with its own term and rate, accounts for taxes on interest, adjusts for inflation, and shows you the real purchasing power of your final balance. This free tool takes the guesswork out of building the perfect ladder.
CD Ladder Calculator
Why a CD Ladder is a Smart Strategy
Certificates of Deposit (CDs) offer guaranteed returns if you keep your money locked in for a set period. However, the penalty for early withdrawal makes them feel restrictive. A CD ladder solves this by staggering your maturities. For example, instead of putting all your money in a 5-year CD, you split it into 4 parts: a 1-year, 2-year, 3-year, and 5-year CD. When the 1-year CD matures, you reinvest it into a new 5-year CD (at the current rate), creating a rolling cycle. This gives you liquidity every year and ensures you’re capturing the highest rates when they rise. As Investopedia notes, this strategy balances yield and accessibility.
How Our Advanced Calculator Works
We’ve upgraded this tool to be your complete CD ladder architect:
- Total Amount: The total money you want to allocate across all rungs.
- Custom Rungs (NEW): Instead of fixed 1, 2, 3, and 5-year options, you can now enter any term for each of the 4 rungs (e.g., 1, 2, 4, 7 years). This allows you to match your ladder to your specific liquidity needs and market outlook.
- Custom Rates: Enter the current APY for each specific term. This is crucial because rates change constantly.
- Tax Rate (NEW): We added a field for your capital gains tax rate. Interest from CDs is generally taxable as ordinary income. We subtract this from your earnings so you see your true net gain.
- Inflation Rate (NEW): Inflation erodes the purchasing power of your savings. Our calculator adjusts your final value to today’s dollars, showing you if your CD ladder is actually protecting your wealth.
- Blended Yield: We calculate the average annual yield of your ladder based on the terms and rates you input.
The Power of Customization
In the past, CD ladders were limited to standard terms. Our calculator breaks this barrier. You might want a 6-month rung for immediate liquidity, or a 10-year rung to lock in a high rate. With our tool, you can enter any combination of terms (e.g., 1, 2, 4, 7 years). We then calculate the future value of each rung, apply taxes, adjust for inflation, and show you the total. This flexibility is essential in today’s dynamic rate environment.
Real-World Example: Sarah’s CD Ladder
Let’s test the calculator with a realistic scenario.
- Total Amount: $50,000
- Rung 1: 1-year, 5.00%
- Rung 2: 2-year, 5.25%
- Rung 3: 3-year, 5.50%
- Rung 4: 5-year, 5.75%
- Tax Rate: 20%
- Inflation Rate: 2.5%
Results:
- Each rung gets $12,500.
- After 1 year, the 1-year CD grows to $13,125 (before tax). Tax is $125, so after-tax value is $13,000.
- After 2 years, the 2-year CD grows to $13,848. Tax is $270, so after-tax value is $13,578.
- After 3 years, the 3-year CD grows to $14,656. Tax is $431, so after-tax value is $14,225.
- After 5 years, the 5-year CD grows to $16,544. Tax is $809, so after-tax value is $15,735.
- Total After Tax: $56,538.
- Real Value (Today’s $):** After adjusting for inflation, the total real value is **$50,000 (roughly break-even).
- Blended Annual Yield: ~5.4% (before tax).
This example shows that while a CD ladder earns more than a savings account, taxes and inflation can significantly reduce your real gains. Our calculator reveals this critical insight.
Why We Added Tax and Inflation Fields
Taxes and inflation are the silent killers of fixed-income investments. If your CD pays 5% but you’re in a 20% tax bracket, your after-tax yield is 4%. If inflation is 2.5%, your real yield is just 1.5%. Our calculator accounts for both, helping you decide whether a CD ladder is truly the best use of your money. For long-term goals, you might need a higher-risk investment to outpace inflation. The Bureau of Labor Statistics publishes inflation data, and the IRS provides tax guidance on interest income.
How to Build a CD Ladder
Your Next Steps: Related Tools
Understanding CD ladders is just one part of your savings strategy. Explore our suite of savings calculators:
- Compound Savings Calculator
- Savings Goal Calculator
- Emergency Fund Calculator
- High-Yield Savings Calculator